Home / Insights / What Is a Financial Audit? Controls and Assurance
FINANCIAL AUDIT
What Is a Financial Audit? Controls and Assurance
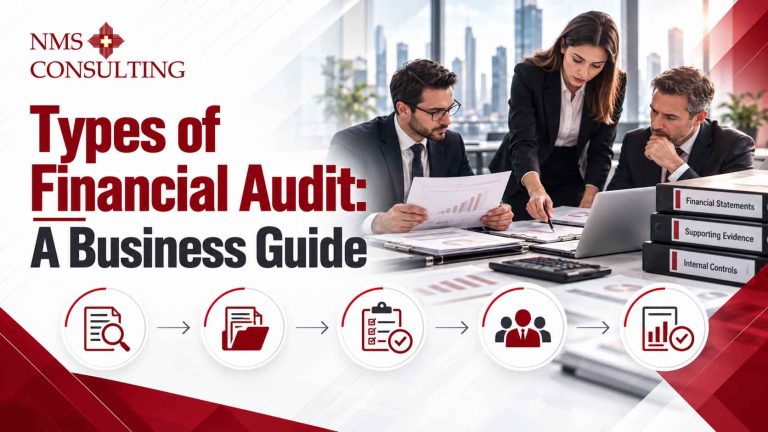
A financial audit involves the examination of financial information under a defined professional mandate. Formal assurance audits differ from internal control reviews, management financial analysis and transaction due diligence, each of which serves a different decision or compliance objective.
QUICK ANSWER
Purpose of a Financial Statement Audit
A formal audit seeks to provide an opinion or conclusion under an applicable assurance framework. It evaluates supporting records, reporting practices and material risk areas as required by professional standards.
Purpose of a Financial Statement Audit
A formal audit seeks to provide an opinion or conclusion under an applicable assurance framework.
It evaluates supporting records, reporting practices and material risk areas as required by professional standards.
The Role of Internal Controls
Financial Information Typically Reviewed
Documented responsibilities, segregation of duties, approvals and reconciliations help maintain reliable information.
Audit Findings and Management Action
Internal control weaknesses can create opportunities for mistakes or fraud even in businesses with strong sales performance.
When Specialist Assurance Is Required
Relevant material may include general ledger records, income statements, balance sheets, cash movements, receivables, inventories, debt and supporting contracts.
What Auditors Examine
Actual procedures depend on the type of engagement and assessed risks.
Internal Controls and Reliability
A management letter or other findings report can highlight issues requiring corrective action.
Company leaders should assign owners and dates, then monitor whether control or reporting improvements are implemented effectively.
Financial Audit and Transaction Reviews
A statutory opinion must be issued by appropriately authorised professionals.
Advisory analysis, internal reporting and financial due diligence are valuable but should not be misrepresented as formal audit assurance.
The scope of a formal financial statement audit depends on applicable standards and risks, but may involve records supporting revenue, liabilities, inventory, balances and important disclosures.
Procedures are designed for the engagement’s assurance objective rather than a guarantee that every mistake or illegal act will be identified.
Authorisation rules, reconciliation, segregation of duties and restricted system access can reduce errors or misuse.
A control must be performed consistently and evidenced, not merely written into a policy.
Responding to Management Findings
Independence and Professional Duties
Organisations should evaluate controls proportionate to their operations and available staff.
Understanding the Audit Process
A buyer considering an acquisition may commission financial due diligence focused on EBITDA quality, working capital and debt-like items.
Audit Scope and Standards
This is distinct from a statutory opinion on financial statements.
Report Purpose and Users
The intended audience and reliance on each report should be clarified before work starts.
Prioritising Recommendations
Recommendations should be ranked by business impact and feasibility.
Remediation and Accountability
Management can assign owners to close documentation gaps, improve reconciliations or address reporting weaknesses, and verify implementation at agreed intervals.
Further Considerations: What Is a Financial Audit
Repeated issues may indicate an underlying process or authority problem. Where law requires an independent or statutory audit, the practitioner must have the relevant status and follow applicable ethics and reporting standards. Internal assessments and consulting services can improve readiness but must not be described as statutory assurance when they are not.
A company preparing for an external financial statement audit should organise its general ledger, reconciliations, accounting policies and evidence supporting material transactions. Depending on the mandate, auditors may evaluate relevant internal controls and carry out procedures addressing significant reporting risks. They generally do not certify that every single transaction is error-free.
Internal audit serves another function: examining the effectiveness of processes, governance and controls according to its organisational mandate. Management advisory and transaction due diligence may use some similar information but differ in objectives, scope and assurance. For example, an acquisition buyer may want to understand recurring EBITDA and hidden debt-like exposures, while a statutory audit opinion is focused on financial statements under a reporting framework.
A business should define the intended users of a report and the reliance they may place on it. Findings need an accountable management response, including deadlines and verification that controls have actually improved. Licensed professional status and independence requirements should be confirmed wherever regulated assurance is required; a consultant’s analytical report should never be presented as an authorised audit opinion.
RELATED SERVICES
Audit and Risk Advisory Services
Financial Management and CFO Advisory
Financial management and CFO advisory covering budgets, liquidity, working capital, financing, cash flow forecasts and board reporting.
Explore Service →
Business Valuation Services
Business valuation services using DCF, market multiples and cash flow analysis for acquisitions, company sales and investor negotiations.
Explore Service →
RELATED GUIDES
Explore Related Articles
SOURCE
The IIA: Global Internal Audit Standards
The 2024 global standards for the professional practice of internal auditing.
Visit Source →
REFERENCES
Official and International Sources
NMS Consulting: management and financial advisory insights.
FREQUENTLY ASKED QUESTIONS
Common Questions About What Is a Financial Audit
What is a financial audit?
It is an independent examination of financial statements and related evidence under the applicable auditing standards.
What does an audit opinion tell readers?
It expresses the auditor’s conclusion on the financial statements under the relevant reporting framework.
Does a clean audit opinion guarantee a company’s financial health?
No. It relates to the financial statements and provides reasonable assurance, not a guarantee of future performance.
How is an audit different from bookkeeping?
Bookkeeping records transactions; an audit independently examines financial statements and supporting evidence.
Can an audit prevent fraud?
An audit may identify material misstatements but cannot guarantee detection of every fraud.
How can management prepare for an audit?
Maintain reconciliations, supporting documents, clear schedules and accountable contacts for audit requests.
Discuss Your Assurance Requirements
Explore relevant management and financial advisory expertise offered by NMS Consulting.